
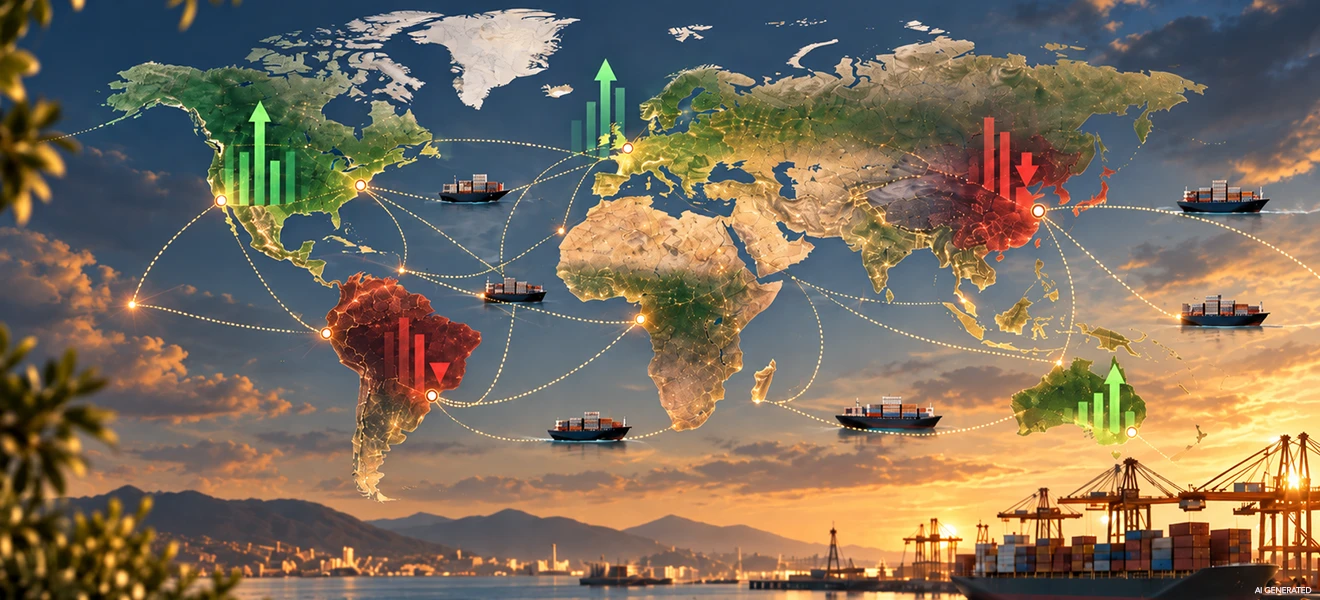
In the first half of 2026, the wine market has seen strong fluctuations: US wine-import value fell 25.2%, while Hong Kong increased more than 20%. Brazil grew in both value and volume, while Japan and Thailand spent more on imported wine despite relatively stable volumes.
For wineries deciding where to export next, the message is clear:
Market selection matters more than ever.
A country can remain one of the world’s largest wine markets while becoming more difficult for new exporters. At the same time, a smaller market can offer attractive opportunities if imports, buyer activity and spending are moving in the right direction.
Here is what the latest H1 2026 trade data tell us — and what those numbers could mean for wineries looking for new importers and distributors.
H1 2026 Wine Imports at a Glance
| Market | Import value vs. H1 2025 | Import volume vs. H1 2025 | Exporter outlook |
|---|---|---|---|
| Hong Kong | +20.4% | +4.5% | 🟢 Strong momentum, especially premium |
| Thailand | +13.7% | -0.2% | 🟢 Worth watching |
| Brazil | +5.9% | +9.1% | 🟢 Clear growth |
| Japan | +5.8% | -0.7% | 🟢 Attractive for premium producers |
| Mainland China | +0.8% | -11.0% | 🟡 Highly selective |
| Canada | -7.9% | -6.8% | 🟡 Weaker momentum |
| United States | -25.2% | -16.8% | 🟡 Huge market, difficult environment |
The Exporter Outlook is a BestWineImporters editorial assessment based on recent import momentum and market characteristics, not a universal ranking. The right market depends on wine type, origin, price position and export capacity.
The contrast between these markets is striking.
The US remains enormously important but experienced a severe contraction. Brazil is moving in the opposite direction. And several Asian markets are showing a particularly interesting pattern: import value is rising much faster than volume.
That distinction matters because growing litres and growing spending do not necessarily create the same opportunity.
United States: The Biggest Warning Signal
The most dramatic decline among the markets reviewed comes from the United States.
Between January and June 2026, the US imported approximately 536.8 million litres of wine worth €2.43 billion.
Compared with the same period in 2025, import volume fell 16.8%, while value dropped 25.2%. The average import price also decreased by 10.1% to €4.52 per litre.
The decline affected most major categories.
Bottled-wine imports were down 26.6% by value. Sparkling wine declined 19.8%, while bulk wine fell 36.4%. Bag-in-box was the notable exception, increasing from a relatively small base.
France and Italy still dominate the market, together accounting for approximately 72% of US wine imports by value during H1 2026. But both suppliers also recorded substantial declines.
Exporter Outlook: HUGE MARKET, HIGHER RISK
This does not mean wineries should abandon the United States.
It does mean that entering the US without careful targeting is becoming harder to justify.
For many producers, the strategy should move away from simply asking:
“How do I find a wine importer in the USA?”
and toward:
“Which importers are still actively buying wines like mine, and in which states?”
That distinction is especially important in 2026 as the US distribution landscape itself is changing. The restructuring around RNDC and the movement of portfolios between wholesalers reinforce how important it is to work with current distributor and importer information.
Brazil: One of the Clearest Growth Stories
Brazil presents almost the opposite picture.
Wine imports reached approximately 79.4 million litres worth €234.3 million in H1 2026.
Volume increased 9.1%, while import value grew 5.9%. The average price declined slightly, by 2.9%, to €2.95 per litre.
Packaged wine was responsible for almost all of that growth, reaching 76.6 million litres and accounting for approximately 96% of imported volume.
The important signal here is that Brazil is buying more wine as well as spending more.
However, volume is growing faster than value, suggesting that price competitiveness remains important.
Exporter Outlook: CLEAR GROWTH
Brazil deserves more attention from wineries looking to diversify beyond traditional European markets and the United States.
It may be particularly relevant for producers with strong mid-market propositions and enough capacity to support commercial distribution.
It should not, however, be approached simply because the headline numbers are positive. Producers still need to identify importers whose portfolios, price ranges and sales channels match their wines.
Hong Kong: Import Value Jumps More Than 20%
Hong Kong recorded one of the strongest results of H1 2026.
The market imported approximately 13.1 million litres worth HK$3.65 billion, around US$465 million, between January and June.
Import volume increased 4.49%, while value jumped 20.37% compared with H1 2025. It was the first simultaneous increase in both measures since 2021.
The difference between volume and value is perhaps the most interesting part of the data.
Hong Kong is buying somewhat more wine — but spending considerably more on it.
That points toward stronger activity in higher-value products rather than simply a broad increase in consumption.
Hong Kong also remains an important regional wine-trading and re-export centre, meaning the opportunity extends beyond its relatively small population.
Exporter Outlook: STRONG MOMENTUM, ESPECIALLY PREMIUM
For premium wineries, fine-wine producers and established brands looking toward Asia, Hong Kong is one of the markets worth reassessing in 2026.
The numbers are especially relevant for exporters whose priority is value rather than high-volume distribution.
Japan: Mature, Stable and Growing in Value
Japan provides another example of why exporters should not look only at litres.
Wine-import volume reached approximately 110.5 million litres in H1 2026, down only 0.72%.
Import value, however, increased 5.8% to JPY121.67 billion, approximately US$757 million.
Japan also remained the largest wine-import market among the Asian economies analysed by Vino Joy.
Unlike an emerging market experiencing double-digit volume growth, Japan is a mature wine market.
That can actually make it attractive for the right producer.
Its restaurant sector, established wine culture and strong demand for premium categories — including sparkling wine — give international wineries access to buyers already familiar with imported products.
Exporter Outlook: ATTRACTIVE FOR PREMIUM PRODUCERS
The Japanese figures suggest resilience rather than rapid expansion.
For premium wineries, regional specialists and producers willing to develop long-term importer relationships, that may be more valuable than chasing a higher-growth but less established market.
Japan is also a good example of why falling volume should not automatically be interpreted as falling opportunity.
Sometimes a market is purchasing slightly fewer litres — but more valuable wine.
Which markets actually fit your wine?
A market can look attractive in trade statistics and still be wrong for your product.
The BestWineImporters Buyer Opportunity Scan narrows the search using your wine category, country of origin, target markets, price position and export capacity — then provides an estimate of relevant importers and sample buyer profiles.
→ Run your free Buyer Opportunity Scan
Mainland China: The Headline Numbers Hide a Major Shift
China remains one of the most complex markets to interpret.
Mainland China imported approximately 101.4 million litres of wine worth US$716.1 million during H1 2026.
Volume declined 10.98%, yet value increased slightly, by 0.83%.
That divergence is important.
China is clearly not returning to the rapid imported-wine growth of the previous decade. But the market is not moving uniformly downward either.
Changes in consumption occasions, growing interest in some white-wine categories and differences between suppliers mean that opportunities can look very different depending on origin and wine style.
This makes China a particularly poor market for exporters to evaluate using headline statistics alone.
Exporter Outlook: HIGHLY SELECTIVE
In a changing market, recent sourcing activity, portfolio composition and buyer fit are much more useful than historical assumptions about China being a universal growth opportunity.
Thailand: A Smaller Market Moving Up in Value
Thailand is considerably smaller than Japan, China or the United States, but its H1 figures deserve attention.
Wine-import volume was essentially unchanged at approximately 9.9 million litres, down just 0.15%.
Value, however, increased 13.71% to THB2.46 billion, approximately US$75.7 million.
Still wine performed better than the overall market, while tourism and changes in Thailand’s alcohol-market framework continue to support hospitality demand.
Again, the important story is not more litres.
It is more money being spent on roughly the same amount of wine.
Exporter Outlook: WORTH WATCHING
Thailand is unlikely to become the first export market for every winery.
But for producers targeting hotels, restaurants, tourism-driven consumption and increasingly premium buyers in Southeast Asia, it deserves a place on the research list.
Smaller markets can also be particularly interesting for wineries whose production capacity makes national-scale distribution in the US or other major markets unrealistic.
Canada: An Important Market With Weaker Momentum
Canada moved in the opposite direction during the first half.
Wine imports declined to approximately 174.6 million litres worth €769.6 million.
Volume fell 6.8% and value declined 7.9%, while the average import price slipped 1.3%.
Packaged wine performed somewhat better than the overall market in volume terms, but still declined in value.
Canada nevertheless remains an established imported-wine destination.
Exporter Outlook: WEAKER MOMENTUM
For wineries already selling into Canada, these figures do not necessarily justify changing strategy.
For new exporters, however, they increase the importance of qualification.
Instead of adding Canada automatically to a list of desirable export markets, producers should first identify whether active importers exist for their particular origin, category and price range.
And What About Europe?
Comparable full-H1 figures are not yet available on the same basis for every major European wine market, so European Q1 results should be viewed separately rather than compared directly with the six-month figures above.
The early data nevertheless point toward relatively weak import momentum.
Germany imported 288.4 million litres worth €585.9 million in Q1 2026, representing declines of 7.8% in volume and 5.3% in value.
UK wine imports were also lower in the first quarter, with value down 5.9% and volume down 4.1%.
The Netherlands recorded declines of 4.5% in value and 3.9% in volume during the same period.
These remain major wine markets. But once again, market size and market momentum are not the same thing.
This article will be updated as additional comparable H1 2026 customs figures become available.
What H1 2026 Means for Wine Exporters
The most important conclusion from the first six months of 2026 is not that wineries should abandon declining markets and rush into whichever country has the largest positive percentage.
The more useful conclusion is:
Export opportunities are becoming more fragmented.
Bigger Does Not Always Mean Better
The United States remains far larger than markets such as Brazil or Thailand.
The right winery, working with the right importer in the right US states, may therefore still find considerably more commercial potential there than in a smaller market growing at double-digit rates.
But the H1 numbers show why automatically choosing the US simply because it is large is increasingly risky.
Market size tells you how much opportunity might exist.
It does not tell you how easy that opportunity will be to capture.
Value and Volume Tell Different Stories
Japan, Hong Kong, China and Thailand demonstrate why exporters need to examine both.
When value grows much faster than volume, the market may be shifting toward more valuable imports.
That can be attractive for premium wineries.
Brazil shows a different pattern: both indicators grew, but litres increased faster than spending.
That may be more relevant for competitively positioned products with the capacity to support broader commercial distribution.
Neither pattern is universally better. It depends on what you sell.
Country Statistics Are Only the Starting Point
Even the best market statistics cannot answer the question that ultimately matters to a winery:
Who is actually going to buy my wine?
A country may have growing wine imports but few appropriate buyers for your price segment.
A declining market may still contain dozens or hundreds of active importers perfectly suited to your category.
A supposedly attractive importer may already represent six direct competitors.
Another may be actively sourcing wines from your country for the first time.
That is why market research needs to move beyond country-level numbers.
So Where Should Wineries Look Next?
Based on H1 momentum alone, Brazil and Hong Kong stand out because both import value and volume are growing.
Japan looks particularly interesting for premium producers because spending is rising despite nearly flat volumes.
Thailand is a smaller opportunity but shows an attractive value-growth pattern.
China remains strategically significant, but it needs to be approached by category, origin and importer rather than on assumptions about the overall market.
The United States remains too important to dismiss, but its H1 contraction reinforces the need for much more targeted importer and distributor selection.
And Canada remains an established destination, although its current momentum warrants a more selective approach.
None of these conclusions means every winery should target Brazil, Japan or Hong Kong tomorrow.
The better process is:
market trend → product-market fit → suitable importer type → qualified companies → decision-maker → outreach.
Already Know Which Market You Want to Target?
BestWineImporters gives wine producers access to 35,000+ verified wine importers, distributors and retailers across 168 countries, including updated company information and contacts for key decision-makers.
Instead of searching Google company by company, exporters can narrow the market using criteria such as location, company type, wine category, product origin, brands, company size and available buyer contacts.